I was just up in Canada this weekend participating in the Whistler Gran Fondo Forte cycling event. Whew…incredibly challenging, beautiful, and rewarding all packaged in 6 hours on my

Dated: June 17 2026
Views: 184
Congratulations!
After weeks—or sometimes months—of looking at homes, writing offers, and wondering if you'll ever get one accepted, you've finally heard the words every buyer wants to hear:
"Your offer was accepted."
For about five minutes, it's exciting.
Then reality sets in.
Most buyers immediately start asking:
"Okay...now what?"
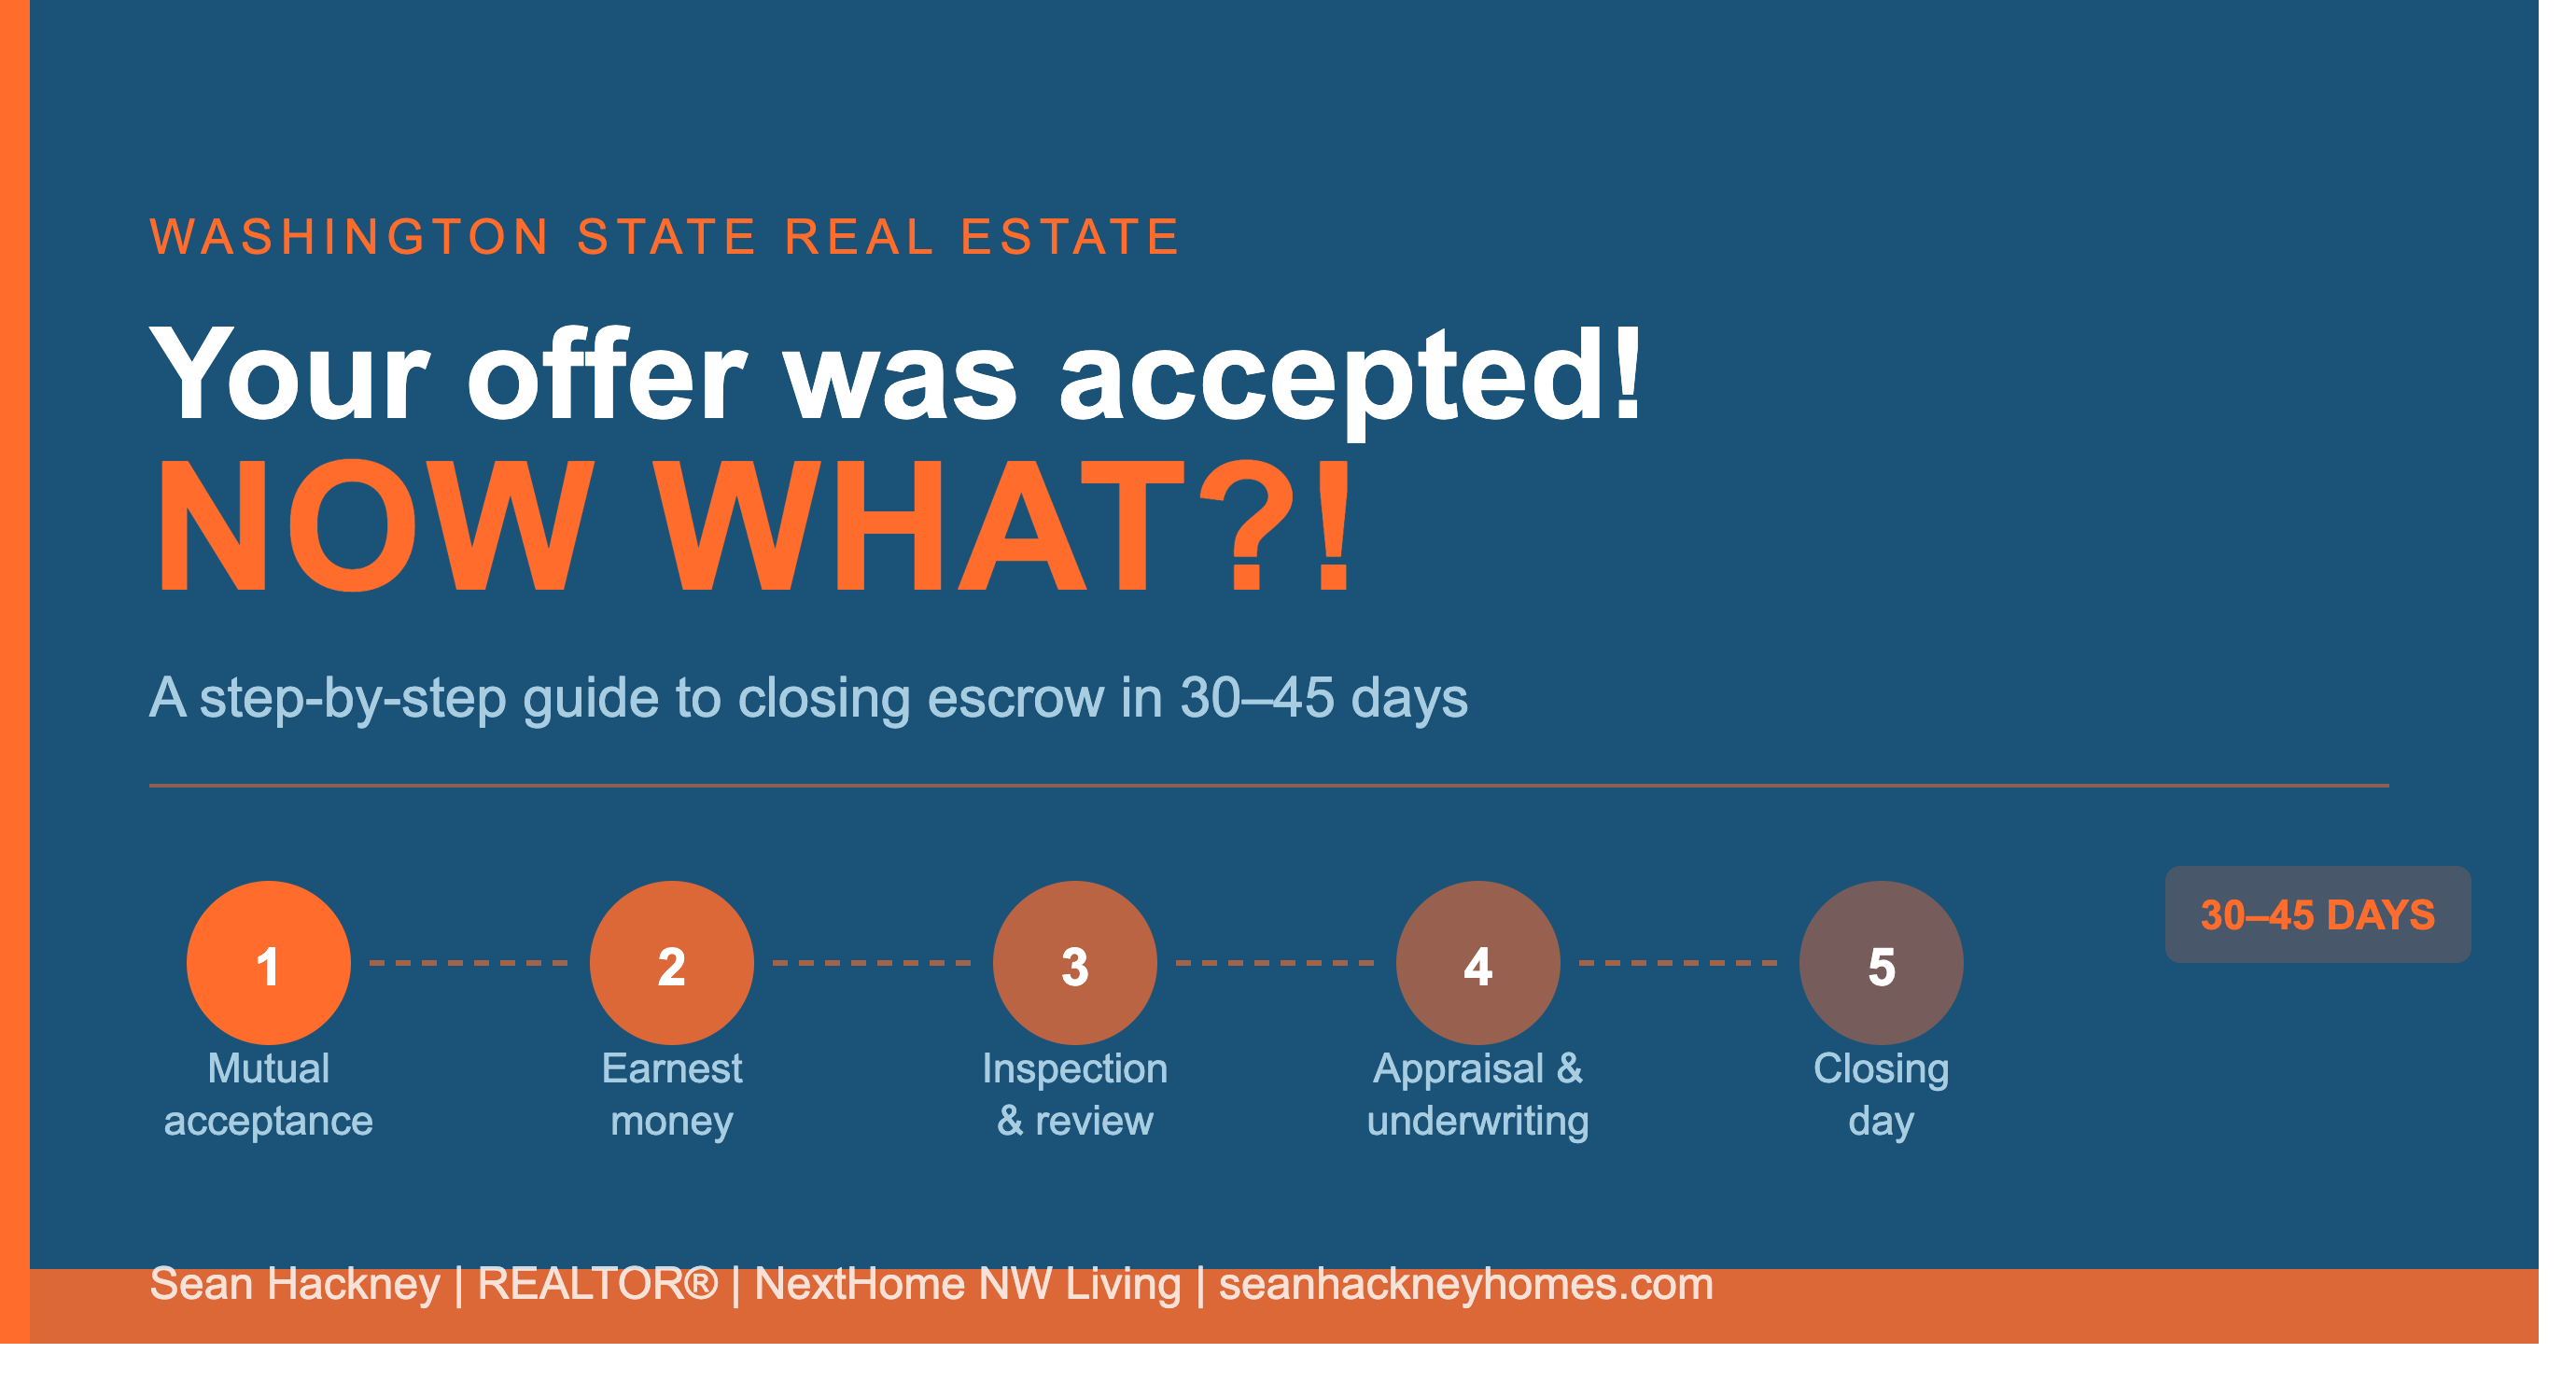
The good news is there really is a roadmap from here to closing day. While every transaction has its own twists and turns, most home purchases in Washington follow a very similar path.
Here's what typically happens next.
The transaction officially begins at what's called mutual acceptance—the moment both buyer and seller have signed the purchase agreement.
From that point forward, the clock starts ticking on all of the deadlines in your contract.
One of the first things you'll do is deliver your earnest money deposit.
Think of earnest money as your good-faith deposit. It shows the seller you're serious about purchasing the home.
At roughly the same time, the escrow process begins. In Washington, a title and escrow company serves as the neutral third party responsible for handling documents, funds, and ultimately the transfer of ownership.
This is also when the title company begins researching the property's history to ensure there are no unexpected issues that could affect ownership.
If there's one part of the process I encourage buyers to take seriously, it's the inspection period.
A home inspection gives you an opportunity to better understand the condition of the property before moving forward.
Depending on the home, buyers may also choose to add:
Sewer scope inspections
Water Quality testing
Pest inspections
The goal isn't necessarily to find a perfect house.
I've never seen one.
The goal is to understand what you're buying and avoid major surprises after closing.
Once the inspection is complete, you'll generally have a few options:
Move forward as-is
Request repairs or credits
Negotiate other solutions
Terminate the transaction if allowed under your contingency
This is often the first major decision point in the transaction.
While inspections are happening, your lender is working behind the scenes.
This is where many buyers feel like they're being asked for the same documents over and over again.
Tax returns.
Bank statements.
Pay stubs.
Updated bank statements.
Another bank statement.
A letter explaining a deposit.
Welcome to underwriting.
The lender's job is to verify that everything in your loan application checks out before they commit hundreds of thousands of dollars to the transaction.
My advice?
Respond quickly.
One of the biggest reasons closings get delayed is because a lender is waiting for documents from a borrower.
If you're obtaining financing, your lender will order an appraisal.
The appraiser's job isn't to determine what you think the home is worth.
Their job is to determine what the lender believes the home is worth.
Most of the time, this isn't a problem.
Occasionally, an appraisal comes in below the agreed purchase price.
When that happens, buyers and sellers have several options, including renegotiating the price or exploring other solutions.
It's not the end of the world, but it can create an unexpected speed bump.
As the closing date gets closer, your lender works toward final approval.
At this stage, it's important not to make major financial changes.
A few things I encourage buyers to avoid during escrow:
Buying a new vehicle
Opening new credit accounts
Making large unexplained deposits
Quitting or changing jobs without talking to your lender
I've seen buyers get excited about furnishing their new home before they own it.
Try to resist the temptation.
Wait until the home is officially yours.
A few days before closing, you'll receive a Closing Disclosure from your lender.
This document outlines:
Your final loan terms
Cash needed to close
Interest rate
Monthly payment
Closing costs
This isn't the time to skim.
Review everything carefully and ask questions if something doesn't make sense.
A good lender and a good Realtor should be happy to walk through it with you.
One of the biggest misconceptions buyers have is thinking they own the home the moment they sign paperwork.
Not quite.
In Washington, ownership officially transfers when the county records the deed.
Most buyers sign documents a day or two before recording actually occurs.
Once recording is confirmed, the transaction is complete, funds are released, and the keys are yours.
That's the moment you've been waiting for.
The buyers who experience the least stress during escrow aren't necessarily the ones with the most experience.
They're the ones who understand the process ahead of time.
Buying a home involves a lot of moving pieces, but none of them should come as a surprise.
Know the steps.
Pay attention to deadlines.
Stay responsive to your lender.
Ask questions.
And remember, your agent should be helping guide you through every stage of the process.
Whether you're purchasing your first home or your fifth, understanding the process ahead of time can make the experience dramatically less stressful.
If you're planning to buy in Bellingham, Ferndale, Lynden, Blaine, Sudden Valley, or anywhere in Whatcom County, I'd be happy to answer your questions and help you understand what to expect before you start writing offers.
No pressure. No obligation. Just real answers and a plan.

Sean Hackney: Your Family-Focused Realtor® Specializing in Relocation, Listings, and Buyers in Whatcom and Northern Skagit Counties Greetings! I'm Sean Hackney, a devoted husband, father, and co-....
I was just up in Canada this weekend participating in the Whistler Gran Fondo Forte cycling event. Whew…incredibly challenging, beautiful, and rewarding all packaged in 6 hours on my
"Sean, I heard you can buy a house here with zero down. Is that actually true?"I get this question a lot from first-time buyers, especially the ones who moved up from Seattle or King County and are
"Sean, the builder says they'll buy down my rate — is that basically free money, or is there a catch?"I get some version of this question every time a buyer starts looking at new construction
You've found the view. The dock's in decent shape, the bulkhead looks solid, and you're ready to write an offer.Here's what I tell every buyer looking at waterfront property in Whatcom County before
 Claims of Copyright Infringement & Related Issues
Disclaimer:
IDX information is provided exclusively for consumers' personal noncommercial use,
that it may not be used for any purpose other than to identify prospective properties
consumers may be interested in purchasing, that the data is deemed reliable but is not
guaranteed by MLS GRID, and that the use of the MLS GRID Data may be subject to an end user
license agreement prescribed by the Member Participant's applicable MLS if any and as amended
from time to time.
The information contained in this listing has not been verified by NextHome Northwest Living and
should be verified by the buyer.
The database information herein is provided from and copyrighted by the
Northwest Multiple Listing Service (NWMLS). NWMLS data may not be reproduced or
redistributed and is only for people viewing this site. Listings that feature the
"three tree" icon are provided courtesy of NWMLS. All information provided is deemed
reliable but is not guaranteed and should be independently verified. All properties
are subject to prior sale or withdrawal. All rights are reserved by copyright.
Based on information submitted to the MLS GRID as of September 21, 2026 5:23 PM UTC. All data is obtained
from various sources and may not have been verified by broker or MLS GRID.
Supplied Open House Information is subject to change without notice.
All information should be independently reviewed and verified for accuracy.
Properties may or may not be listed by the office/agent presenting the information.
Some IDX listings have been excluded from this website.
Copyright 2026 Northwest Multiple Listing Service. All rights reserved.
